Home sellers and buyers warned to move quickly if they want to benefit from the stamp duty holiday – as owners over-estimate their property’s worth
- Property sellers need to market their home by the end of September
- NAEA Propertymark said this will maximise their chances of getting the transaction in before the 31 March 2021 stamp duty deadline
- Aviva survey suggests recent house price surge has led many homeowener to overstimate how much their property is worth
- Setting a realistic asking price was among five tips issued by NAEA Propertymark to expedite the home-selling process
Households looking to take advantage of the stamp duty holiday to buy or sell their home have been warned by estate agents to get moving within weeks.
Property sellers need to market their home by the end of September if they want to maximise their chances of getting the transaction in before the 31 March 2021 stamp duty deadline, according to NAEA Propertymark.
The estate agent body said that with the property market ‘thriving’ post-lockdown while many conveyancing services are running at Covid-reduced levels, the home-selling process from marketing to completion could take much longer than expected.
Setting a realistic asking price was among five tips issued by NAEA Propertymark to expedite the home-selling process (see box below).
Mortgage applications and surveys are reportedly suffering delays amid backlogs and staffing issues.
And many buyers are now thought to be sitting on the sidelines, hoping for prices to moderate over the next few months, while still aiming to get in under the deadline to benefit from the stamp duty holiday.
A series of surveys over the summer have revealed a post-lockdown surge in the British housing market. NAEA Propertymark itself reported that an average of 13 sales per estate agent branch were agreed in July, the highest figure recorded since June 2007.
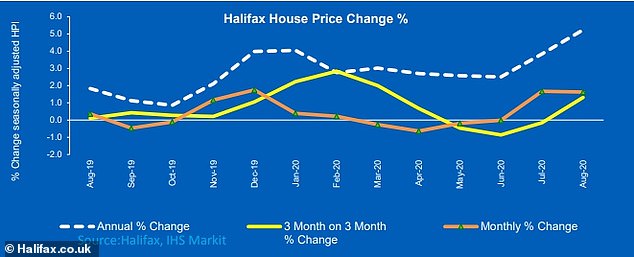
Halifax said recently that the spike in house price inflation is ‘highly unlikely’ to continue. The lender’s latest house price index revealed that the average property price increased by 5.2 per cent annually to reach a record £245,747 in the year to August.
The Royal Institution of Chartered Surveyors this week said that virtually all parts of the UK are now seeing prices increase to some extent, with buyers facing a ‘sharp acceleration’ in prices up and down the country in August.
Rics added that, with the sharp gains coming at the same time as a mortgage crunch and job losses, many buyers could be squeezed out of the market.
But experts have also warned that the mini-boom could unravel once the true economic toll of the pandemic starts to bite later this year and job losses mount.
Halifax said recently that the spike in house price inflation is ‘highly unlikely’ to continue. The lender’s latest house price index revealed that the average property price increased by 5.2 per cent annually to reach a record £245,747 in the year to August.
According to one survey, since house prices started surging this summer, homeowners have begun to overestimate their property’s value.
Insurer Aviva’s survey of more than 2,300 homeowners found that, on average, people estimated the value of their home at £288,263. This is £52,590 higher than the average UK house price in May of £235,673 as recorded by the Office for National Statistics.
Homeowners in Northern regions appear to be most prone to overvaluing their homes with the North West and North East showing some of the biggest discrepancies (see box right).
London were the only ones who typically appeared to under-estimate the value of their property.
Indeed, setting a realistic asking price was among five tips issued by NAEA Propertymark to expedite the home-selling process.
Recent Comments